What Is a 2-1 Temporary Buydown?
When mortgage interest rates sit above the ultra-low levels many buyers recall, finding creative financing pathways to lower initial payments becomes a top priority.
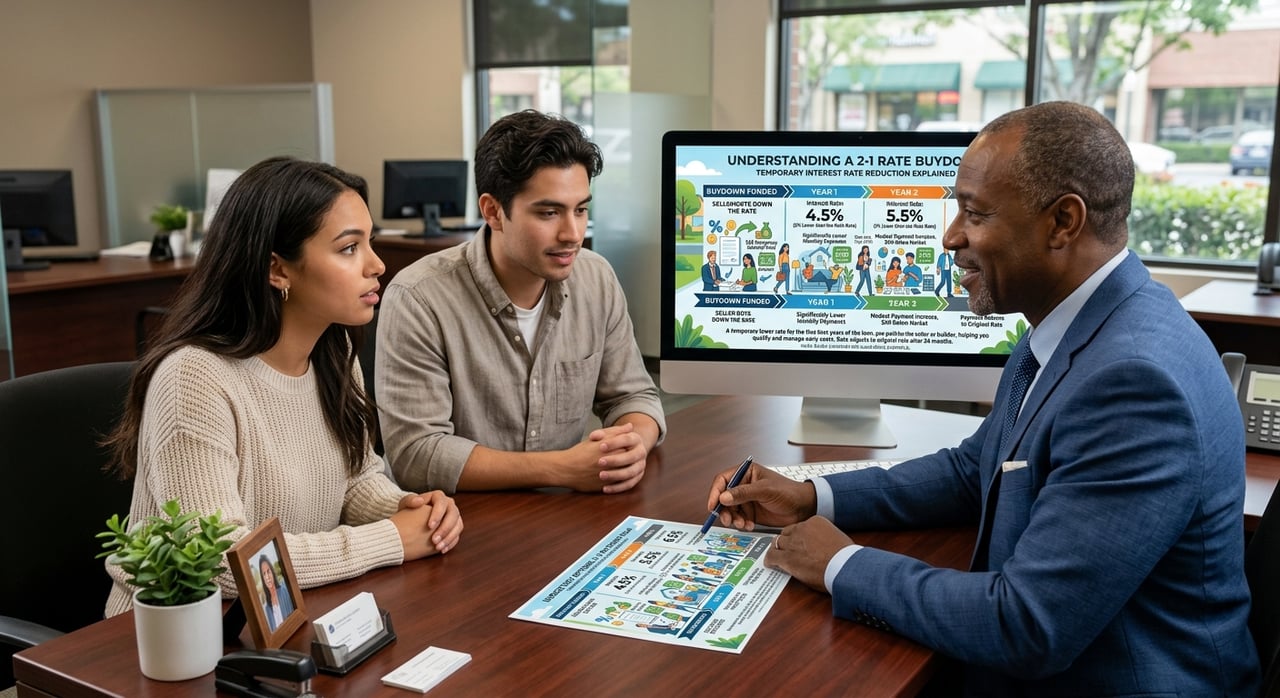
One effective strategy is a 2-1 temporary buydown. This mortgage solution reduces your effective interest rate during the first two years of a qualifying fixed-rate loan before returning to the full note rate.
The standard step-down framework operates as follows:
Year 1: Interest rate is 2.00% below the note rate
Year 2: Interest rate is 1.00% below the note rate
Year 3 and beyond: The loan returns to the full fixed note rate for the remaining loan term
For example, if your fixed note rate is 7.00%, a 2-1 buydown establishes an effective payment rate of 5.00% in Year 1, 6.00% in Year 2, and 7.00% beginning in Year 3.
How Does the Payment Reduction Work?
A temporary buydown does not permanently alter the promissory note rate.
Instead, a lump-sum subsidy is deposited into an escrow buydown account at closing. Each month during the first two years, funds from that account release automatically to cover the difference between your reduced payment and the full principal-and-interest amount owed to the lender.
These subsidy funds are typically provided through seller concessions, builder incentives, or lender credits, making the buydown a powerful financing instrument when navigating purchasing a home in Stanislaus County.
A Simple Turlock Payment Example
To illustrate the monthly relief, imagine purchasing a $500,000 home in Turlock with an initial loan amount of $475,000 on a 30-year fixed loan at a 7.00% note rate:
Period | Effective Interest Rate | Monthly Principal & Interest | Estimated Monthly Savings |
Year 1 | 5.00% (2% below note) | ~$2,550 / month | Save ~$610 / month |
Year 2 | 6.00% (1% below note) | ~$2,848 / month | Save ~$312 / month |
Years 3–30 | 7.00% (Full note rate) | ~$3,160 / month | Standard Fixed Payment |
(Note: Figures represent principal and interest only. Total monthly payments include Stanislaus County property taxes, homeowners hazard insurance, and any applicable private mortgage insurance.)
During the first twelve months, saving over $600 each month ($7,320 in Year 1) provides crucial cash-flow flexibility while settling into a new property.
Who Typically Pays for a 2-1 Buydown?
While buyers can technically fund their own buydown, it is most advantageous when negotiated as an interested-party contribution:
Seller Concessions: A motivated seller contributes a credit toward your buydown rather than dropping their headline price.
Builder Incentives: Developers offer rate buydowns to move standing new-construction inventory.
Lender Credits: Structured credits applied directly to closing costs.
In competitive Central Valley transactions, this creates a win-win negotiation lever. A seller might hesitate to lower their listing price by $12,000 because it affects perceived market value or neighborhood comps. However, offering that same $12,000 as a closing concession to fund your 2-1 buydown delivers far more monthly payment relief than a minor price cut ever could.
If you are planning to sell an existing property to finance your next move, checking your complimentary home valuation helps you calculate how much seller concession room you can realistically offer prospective buyers.
Why Might a Central Valley Buyer Consider One?
A 2-1 temporary buydown is particularly well-suited for buyers who anticipate rising income, or who simply desire cash-flow breathing room while furnishing and adjusting to a new home:
Initial Cash-Flow Relief: Substantially lower payments during the most expensive phase of homeownership—the initial move-in and setup period.
Budget Ramp-Up: Step-up payment increases over 24 months give household budgets time to adapt gradually.
Strategic Refinance Window: If mortgage interest rates decline during your two-year window, you can explore a wholesale mortgage refinance to lock in a permanently lower rate. (Any unused funds remaining in the escrow buydown account are credited directly against your principal balance at payoff.)
Crucial Underwriting Rule: Buyers must qualify for the mortgage based on the full note rate (or applicable agency qualification benchmarks), ensuring you are financially qualified to sustain Year 3 payments without relying on an assumed refinance.
Weighing the Trade-Offs
Before committing to a temporary buydown, evaluate the full cost structure against alternative negotiation strategies:
Buydown Cost vs. Price Reduction: Does an upfront seller credit save you more cash flow than an outright reduction in purchase price?
Permanent Rate Buydown (Discount Points): Would paying discount points for a permanent rate reduction provide better 10-year value than two years of temporary relief?
Long-Term Comfort: Are you completely comfortable making the full Year 3 payment if interest rates remain unchanged and refinancing is not viable?
Comparing custom loan scenarios with a dedicated wholesale mortgage broker ensures you identify the most cost-effective structure for your specific timeline.
Why Work With Great Central?
Evaluating seller concessions, purchase contracts, and mortgage underwriting simultaneously requires seamless coordination.
At Great Central Realty and Great Central Mortgage, our dual-licensed structure operates under one roof:
Great Central Realty identifies opportunities on active homes for sale across Turlock and Stanislaus County, assessing seller motivation to negotiate targeted concession credits.
Great Central Mortgage runs precise mathematical scenarios comparing temporary buydowns, permanent discount points, and standard fixed financing across multiple wholesale lending channels.
This unified representation guarantees that your contract terms and your mortgage structure work toward one goal: maximizing your monthly affordability and protecting your capital.
Explore Your Home Buying & Financing Options
Do not assume current headline rates restrict your homeownership goals:
Get pre-approved with Great Central Mortgage to run custom 2-1 buydown payment breakdowns based on your target price point.
Search active Central Valley listings to identify properties currently offering seller incentives or price flexibility.
Need to review an existing loan? Explore current mortgage refinancing programs.
Contact our local team today to discuss how a structured seller buydown can strengthen your next purchase offer.